Nigeria's two biggest fintech competitors are building enormous payment networks, but their financial disclosures reveal two different businesses emerging from the same market. OPay has demonstrated that its scale can translate into profitability. Moniepoint has disclosed a formidable transaction network but has yet to provide comparable consolidated earnings figures.
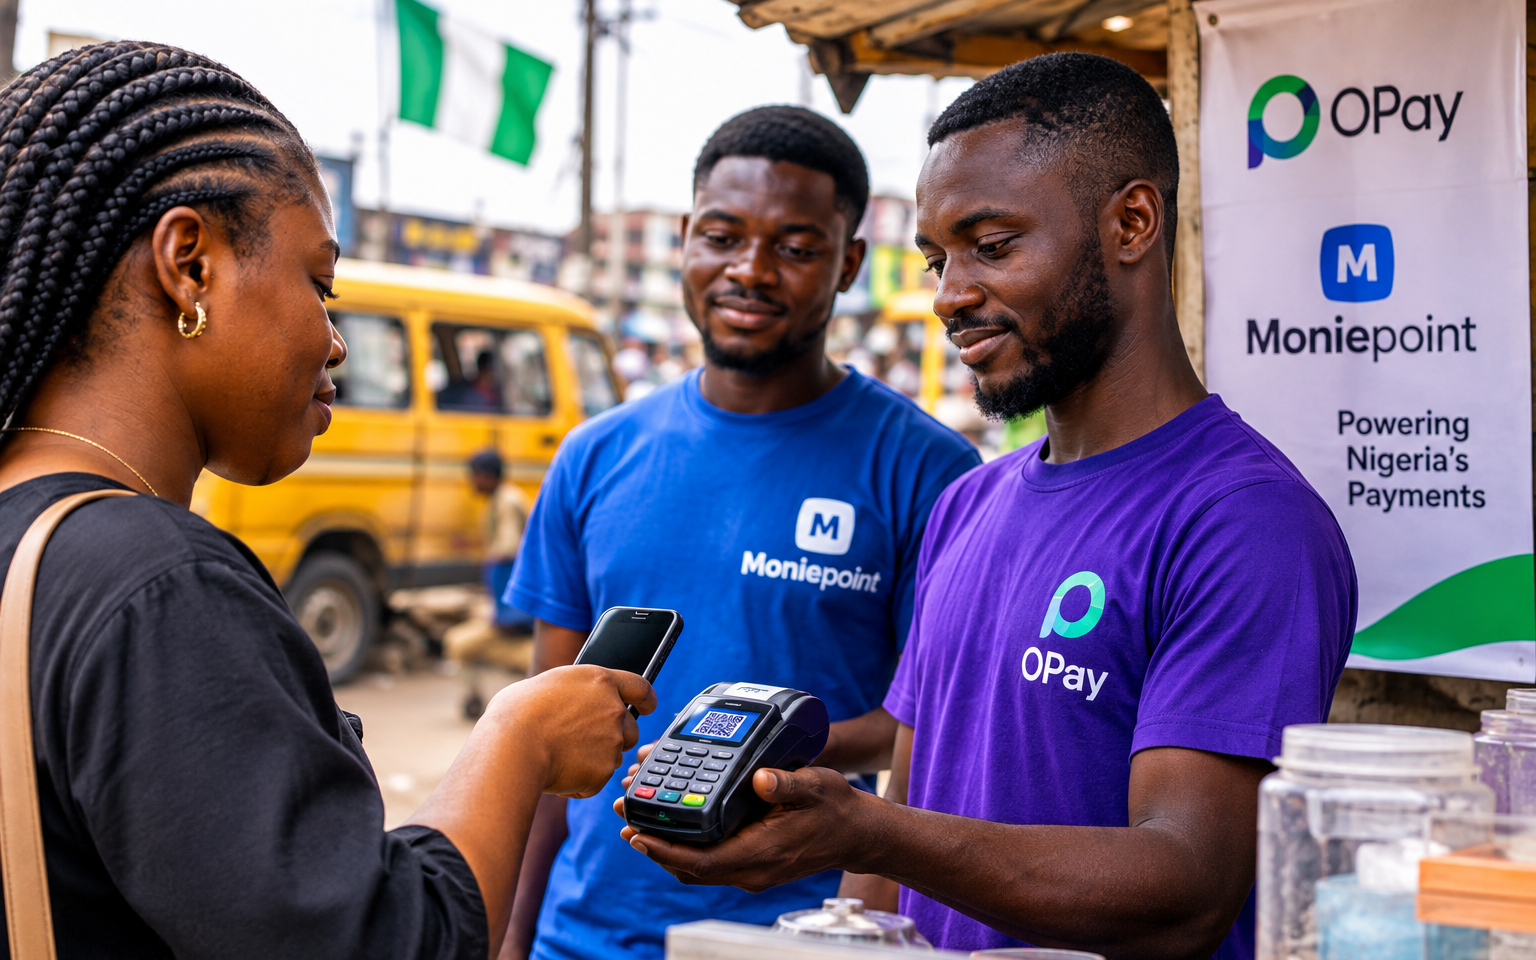
For millions of Nigerians, the difference between the two companies is often a matter of convenience. It is the agent around the corner who can turn cash into a bank transfer, provide cash when an ATM is empty or help a small business collect payments without a traditional banking terminal.
Behind those everyday transactions, however, OPay and Moniepoint are competing for something considerably bigger: control of the infrastructure through which Nigeria's informal and formal economies increasingly move money.
The scale is already substantial. Nigeria had approximately 6.54 million PoS terminals by December 2025, up from 5.56 million at the end of 2024, according to the Central Bank of Nigeria's December 2025 Financial Stability Report. The figure captures the continued expansion of the country's payment infrastructure, although the CBN's latest report does not specify how many of those terminals were actively processing transactions. Its last explicitly reported active-terminal figure was 5.90 million in March 2025. The country also has more than two million financial access points and agents nationwide, according to the CBN's Nigeria Payments System Vision 2028. Together, these figures show how deeply agent banking has become embedded in Nigeria's financial system.
Who is moving more money?
Both companies are processing transaction values that would have been difficult to imagine in Nigeria's payments market a decade ago.
OPay reported $358 billion in gross transaction value (GTV) in 2025, more than double the $166.2 billion recorded in 2024. Its prospectus, filed with the US Securities and Exchange Commission, attributes the growth partly to an expansion in daily active users, which increased from 15.1 million to 22.7 million.
Moniepoint, meanwhile, processed more than 14 billion transactions worth approximately ₦412 trillion in 2025, according to an internal company presentation reviewed by TechCabal. The publication estimated the transaction value at approximately $294 billion using its exchange-rate conversion. Moniepoint's figures represent a substantial expansion from the 5.2 billion transactions and $182 billion in transaction value it reported for 2023.
The numbers suggest that both companies have become major forces in Nigeria's payments ecosystem. However, they should not be treated as a direct market-share comparison.
OPay operates across several markets, including Nigeria, Egypt and Indonesia, although Nigeria accounted for 88.1% of its 2025 revenue. Moniepoint's ₦412 trillion figure covers activity across its subsidiaries and business lines, rather than PoS transactions alone.
The distinction matters because a transfer processed through a mobile application, a payment collected through a merchant terminal and a transaction routed through an online gateway are not necessarily competing for the same customer or revenue.
The battle for Nigeria's agents
Transaction volumes tell only part of the story. In agent banking, distribution is often just as important as technology.
Moniepoint says it operates more than one million active terminals. TechCabal has also reported that the company has more than 400,000 active agents and accounts for approximately 42% of Nigeria's PoS transaction volume. The latter market-share estimate should be treated as a published industry estimate rather than an independently verified regulatory figure.
OPay, for its part, has previously disclosed the deployment of hundreds of thousands of PoS devices. However, the number of terminals distributed or dispatched is not equivalent to the number currently active, and the company has not provided a directly comparable active-agent figure.
That distinction makes it difficult to establish which company has the larger operational network. The competitive environment is also changing because of regulation.
Under its revised Guidelines for the Operations of Agent Banking, issued on October 6, 2025, the CBN introduced an exclusivity requirement restricting agents to one principal at a time. The provision, alongside agent-location requirements, became effective on April 1, 2026.
Previously, an agent could maintain relationships with several providers, switching between terminals when one network experienced downtime or offering customers alternatives. Under the new arrangement, an agent must commit to a single principal for its agent-banking operations.
The CBN also introduced geofencing requirements in August 2025, requiring PoS terminals to operate within their registered locations. Following complaints about the original 10-metre restriction, the regulator expanded the permitted radius to 70 metres and extended the compliance deadline to August 1, 2026.
These changes could reshape competition. Providers will have to work harder to attract and retain agents, while smaller operators may find it more difficult to access the distribution networks that previously allowed them to compete with larger platforms.
For OPay and Moniepoint, the ability to offer reliable transactions, attractive agent economics and dependable customer support could become more important than simply putting more machines into circulation.
How much money does the business actually make?
This is where OPay's financial disclosures provide a more revealing picture. The company generated $536.25 million in revenue in 2025, compared with $205.73 million in 2024, representing growth of approximately 161%.
Its gross transaction value reached $358 billion, but dividing total revenue by that figure produces a ratio of approximately 0.15%. That is not OPay's actual payments take rate because the revenue figure includes lending, loan facilitation, investment income and other services.
The more appropriate comparison is its transaction-based revenue. This increased from $79.19 million in 2024 to $167.26 million in 2025. Against the $358 billion transaction value, that represents approximately 0.047%, or about 4.7 cents for every $100 processed.
Even this is a broad platform-level ratio rather than the fee earned on every individual PoS transaction.
The more significant development is the growing contribution of lending. Loan financing generated $260.25 million, accounting for 48.5% of OPay's 2025 revenue. Transaction-based services contributed $167.26 million, or 31.2%. Loan facilitation and other income streams accounted for the remainder.
OPay originated $938.3 million in new loans in Nigeria during 2025, up from $243.9 million in 2024. Its quarterly unique borrowers also increased from 2.1 million to 4.6 million.
This shift suggests that OPay is becoming more than a payments company. Its large customer and merchant network is increasingly serving as a distribution channel for credit.
However, lending brings a different set of risks. OPay's provision for expected credit losses increased from $24.8 million in 2024 to $121.3 million in 2025. That does not mean the entire amount represents loans already lost, but it highlights the financial exposure that accompanies rapid credit expansion.
The quality of its loan book will therefore be just as important as the growth in its transaction volumes.
OPay is profitable. What about Moniepoint?
OPay's financial turnaround is already visible. The company reported a net profit of $72.47 million in 2025, reversing a $50.98 million loss in 2024. Its performance strengthened further in the first half of 2026, when revenue reached $467.06 million and net income rose to $90.9 million.
Moniepoint has disclosed impressive growth but offers less visibility into its overall profitability.
The company says it provided more than ₦1 trillion in credit to small businesses in 2025. It has also highlighted the relationship between access to its financial services and business growth, including a reported 36% increase in transaction value among its borrowers.
These are meaningful indicators of business activity, but they do not establish how much profit Moniepoint retains after operating expenses, funding costs, provisions for bad loans and other obligations.
Without comparable consolidated financial statements, it is premature to conclude that one company has a stronger underlying business simply because its transaction network appears larger.
The distinction is important: transaction volume measures activity, revenue measures monetisation, and profit shows what remains after the cost of running the business.
The IPO that changed the conversation
OPay's attempt to enter the US public markets was expected to provide investors with a clearer picture of the company's financial performance and give African fintechs another significant international listing.
After its registration statement became effective on October 29, 2026, the company announced the pricing of 16 million American depositary shares at $19 each on October 30, valuing it at approximately $4 billion and aiming to raise $304 million. However, hours after ringing the opening bell, its shares failed to begin trading on the New York Stock Exchange.
The company said the inquiry concerned a jurisdiction that was immaterial to its core business operations and maintained that the decision should not be interpreted as a reflection of its financial performance or regulatory standing.
Bloomberg subsequently reported that the inquiry involved a Chinese regulator, citing people familiar with the matter. OPay did not publicly identify the regulator or disclose the precise subject of the inquiry.
The failed listing does not erase the company's financial progress, but it demonstrates that strong operating numbers alone do not guarantee access to international capital markets. Regulatory scrutiny, corporate governance and investor confidence remain equally important.
Nigeria's PoS competition is entering a different phase. The early contest was about getting terminals into markets, shops and neighbourhoods. The next phase will be about controlling distribution, retaining customers, managing credit risk and turning enormous transaction volumes into sustainable earnings. OPay has demonstrated that it can convert scale into reported profitability, although its growing dependence on lending introduces risks that investors will need to monitor. Moniepoint has established a formidable transaction network, but greater financial disclosure would help determine how much of that scale translates into durable profit. The CBN's exclusivity rules add another dimension by making agents a more contested strategic asset. A provider that loses access to a productive agent may lose not just a terminal location but an entire stream of customer relationships and transaction activity. Ultimately, the winner will not necessarily be the company processing the most transactions or distributing the most machines. It will be the one that can keep agents productive, customers loyal and transactions profitable without taking on risks that undermine the business. In a market where both companies already move hundreds of billions of dollars, the more important question is no longer how much money passes through their networks. It is how much value they can sustainably keep.
Source archive dated 16 Nov 2026. This article is not a live update.
AI Generated
Request a correction →